

Opinion: Most Prediction Market User Behavior Has No Predictive Value
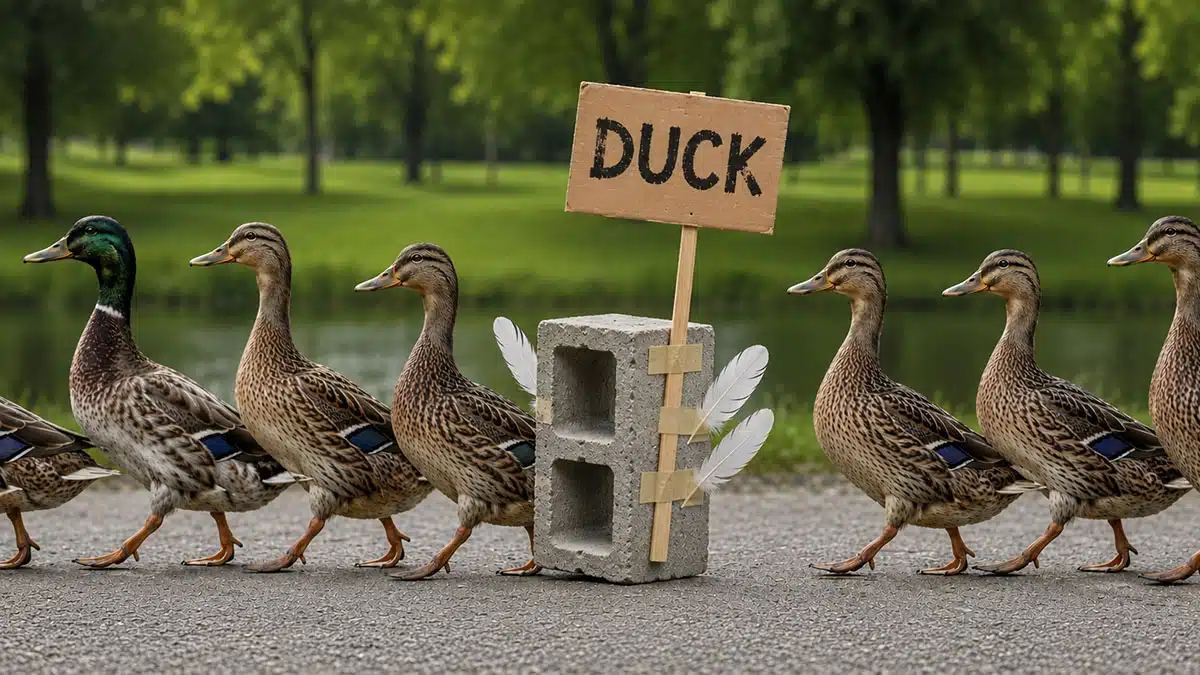
To be fair, it's a pretty convincing disguise.
Prediction markets face a number of problems in their fight to defend their legitimacy, and the way users interact with the platforms may become another.
“If it looks like a duck, walks like a duck, and quacks like a duck — then it’s a duck,” as the old adage goes. But if prediction markets hope to present themselves as economically useful financial platforms, they aren’t doing a good job of selling that disguise.
Central to the various legal cases by and against Kalshi and its ilk is the question of whether they are gambling products or financial products. Their survival depends on being classified as the latter. Financial products, however, are expected to have economic utility, not just entertainment value.
From the start, prediction markets have trumpeted their supposed usefulness on two fronts: risk hedging and forecasting power. And yet, what contracts their users choose to trade and when most of that trading happens tend to undermine the idea that many people are using them to hedge or that those traders are providing any useful insight in the process.
Last week, Kalshi suffered a significant blow as the Ninth Circuit ruled, in essence, that it neither looks like a duck nor quacks like a duck. The court found that Kalshi’s sports contracts bore less resemblance to swaps than they did to bets. Moreover, the platform’s own advertising had repeatedly used words like “bet,” rather than financial terminology.
By contrast, the question of whether it at least walks like a duck has gotten relatively little attention. Yet, how users interact with the product in practice has the potential to become legally important during the seemingly inevitable Supreme Court showdown or legislative hearings.
Kalshi has already shot itself in the foot once with its advertising. Some of the types of contracts it chooses to offer may be similarly damaging, precisely due to their popularity.
Ultra-Short Term Markets Are of Questionable Predictive Value
Usually, when we’re talking about forecasts or predictions, the expectation is of a reasonable lead time. Especially in an economic context, those receiving the information need enough lead time to act on it.
When it comes to sports, bettors overwhelmingly prefer to make their wagers during a game or immediately before it. Even if you were, say, running a local business whose profits depend on whether your city hosts a playoff game this year, there’s no real difference in knowing the result of the current game at halftime or at the final whistle. Any strategic planning based on the result is likely to wait for the next management meeting either way.
More tellingly, though, we can look at how Kalshi users interact with commodity markets. Here, there’s a clear case for the value of predictive power over longer timescales. If you’re running a shipping business, for instance, it’s definitely important to know whether the cost of oil is going up or down this year.
However, almost no one trades in those longer-term up-or-down markets on Kalshi. In recent months, it rolled out daily and hourly markets that performed significantly better. The real magic bullet, however, has been 15-minute markets, seemingly designed to appeal to the same group of algorithmic traders who flocked to the 15-minute crypto markets introduced last year on Polymarket.
We’re talking about orders of magnitude more trading on these markets than on even the weekly or monthly markets, let alone year-long contracts. In the span of a few weeks, Kalshi has expanded the lineup from gold, silver, and oil to include copper and natural gas, and all of these are consistently among the most traded contracts not related to sports or crypto.
It’s hard to see who would benefit from forecasts over such a short timescale, other than the exact same people trading in those markets.
Trading on Things That Already Happened
The extreme difference in popularity between longer and shorter-term markets suggests that instant gratification is important, which is typical of gamblers. Observing the communities around prediction markets, many of these users are or believe themselves to be advantage gamblers. The 15-minute turnaround is appealing because it presents a faster way to grind out a profit if they can find an edge.
Even better than a quick turnaround, from a gambler’s perspective, is a sure bet. For political markets, especially, we see the bulk of trading happen after an announcement. Once the outcome is known, traders flock to the sites to wring out a few pennies’ worth of profit before the market settles or the liquidity dries up. This behavior is known as “bonding” — a reference to bonds as safe but low-yield investments.
Clearly, there’s no predictive value in bonding. The prediction markets’ signal trails the mainstream media’s when that happens.
Sometimes, it’s even the case that contract prices don’t go immediately to zero or a dollar after an announcement, and trading continues for hours or days after. In these cases, it’s usually because the contract rules themselves are ambiguous. Sometimes, millions of dollars change hands not over what will happen, but on how a site’s resolution board or process will define what already did happen.
Extreme Longshots Are Popular in Multiway Markets
At the opposite pole from bonding is the tendency of a smaller segment of prediction market users to scoop up extreme longshots in markets that are still far from resolving. Haiti, for instance, accounted for an unusually large amount of pre-tournament World Cup volume this summer.
That, too, is typical of gamblers. It may or may not distort the markets, but it does undermine the usefulness of “volume” as a measure of market reliability. If the Yes shares of a given prospect are trading at one cent, then 99% of the nominal volume for that contract is held by institutional liquidity providers who aren’t really expressing an opinion about the true likelihood, since they hold the No side of every other option as well.
Looking at something like the 2028 Democratic Presidential Nominee market, someone could legitimately have an economic interest in who ultimately runs. And looking at the $210 million in volume to date, they might assume that the odds on Gavin Newsom — the favorite until very recently — represent widespread consensus.
In reality, however, only about $7 million — less than 5% — of that volume was on Newsom. Other likely possibilities, such as Alexandria Ocasio-Cortez or Jon Ossoff, aren’t much more heavily traded. Instead, inspect the trades on any given day and you might find five-figure volumes on someone like LeBron James or Dwayne ‘The Rock’ Johnson. Those often come from a single trader taking, say, a $100 flier at 500-1 odds, and don’t represent any sort of market consensus.
Information Value is Incidental to Prediction Platforms’ Business
That’s not to say election markets have no predictive value. They are, perhaps, the best argument in prediction markets’ favor. Yet those markets make up only a tiny fraction of total volume, while sports account for the bulk. And only an even tinier fraction of that political volume can be said to be predicting anything.
To the extent that prediction markets have any forecasting power, it appears to arise incidentally from a minority of the transactions. The majority do not provide a useful signal because they “predict” events that are either just about to happen, have already happened, or are never going to happen.
If there’s a signal there, there’s also a lot of noise. And the more prediction markets focus on the offerings that appeal to recreational bettors and algorithmic speculators, the more they’ll amplify the noise. That, in turn, makes it ever harder to convince anyone that the signal is the point.
Players trust our reporting due to our commitment to unbiased and professional evaluations of the iGaming sector. We track hundreds of platforms and industry updates daily to ensure our news feed and leaderboards reflect the most recent market shifts. With nearly two decades of experience within iGaming, our team provides a wealth of expert knowledge. This long-standing expertise enables us to deliver thorough, reliable news and guidance to our readers.
Latest News